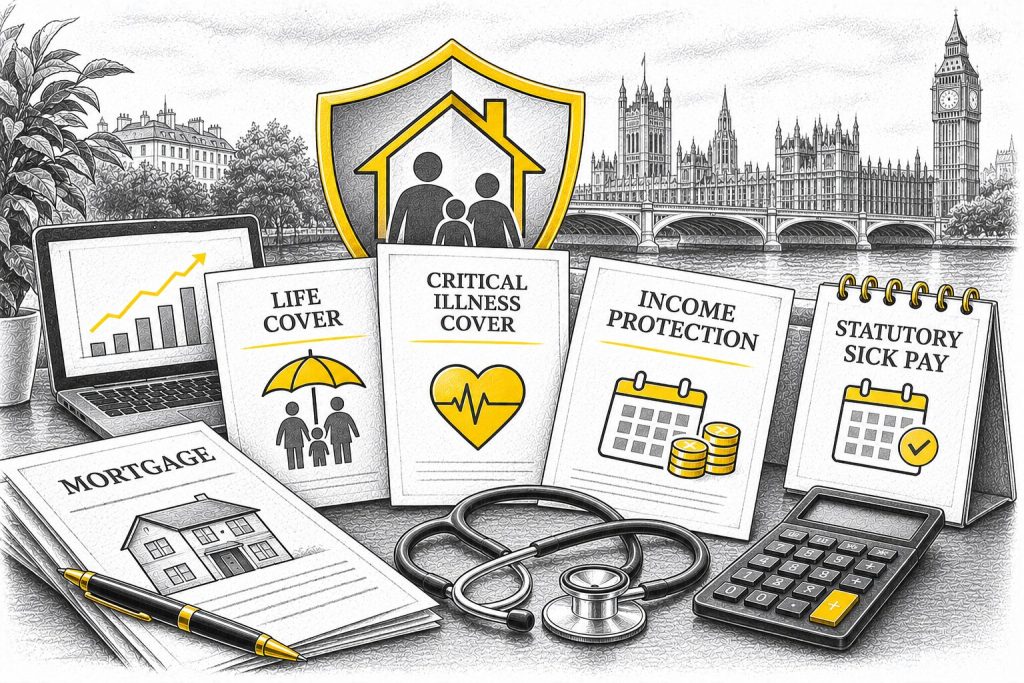

When did you last review your Protection Policies?
One of the biggest mistakes people make with life insurance is treating it as a one-off job.
They take out a policy, file it away, and assume that because they have cover in place, the job is done.
In our view, that is where people can come unstuck.
Having a life policy is not the same as having the right life policy.
And if it has not been reviewed in years, there is every chance it no longer reflects what is actually going on in your life.
Life changes. Your protection should too.
Life insurance is usually arranged at a key moment.
That might be when you buy your first home, take on a bigger mortgage, get married, have children or start thinking more seriously about what would happen if your family lost your income or support.
The problem is that life does not stay still after that.
People move house. Borrow more. Have more children. Change jobs. Start businesses. Build wealth. Separate. Remarry. Take on new responsibilities. Clear debts. Accumulate other policies they barely remember arranging.
Yet the protection is often left exactly where it was.
That makes no sense.
If your life has changed, your cover should be reviewed. It is as simple as that.
Too many people assume “I’ve got a policy, so I’m covered”
This is probably the most common misunderstanding we see.
People know they have life cover somewhere, but they are not always clear on how much it is for, how long it runs for, who it is meant to protect or whether it still matches the reason it was taken out in the first place.
That is not proper protection. That is just having paperwork.
In our opinion, life insurance should be far more deliberate than that. It should be there for a clear purpose, and that purpose should still be relevant today.
If it was originally set up to cover a mortgage, does it still cover the mortgage you have now?
If it was meant to protect your family, would it still realistically do that based on your current lifestyle and outgoings?
If it has been sitting there untouched for years, those are fair questions to ask.
Mortgage changes are a major reason to review cover
This is a big one.
When people move home, remortgage, borrow more, extend their term or restructure their mortgage, they often focus entirely on the finance side and forget to revisit the protection.
But the two should go hand in hand.
A policy arranged for an old mortgage balance may no longer be enough.
A policy taken over a shorter term may no longer align with the new mortgage term.
A client may now have multiple bits of cover sitting in different places without a clear understanding of what each one is doing.
We see this quite a lot.
The protection only works properly if it still matches the liability it was designed to protect.
Family circumstances can outgrow old protection very quickly
A policy that felt perfectly fine five or ten years ago may feel very different once life moves on.
That is especially true where children are involved.
The level of cover you thought was enough before nursery fees, school costs, rising household bills and a larger mortgage may no longer feel anywhere near as reassuring now.
This is where reviews matter.
Because the question is not whether you technically have life insurance. The real question is whether the people relying on you would actually be protected in the way you think they would.
That is a much more important conversation.
Reviewing a policy does not always mean replacing it
This is important.
A review is not about changing something for the sake of it.
In many cases, the right answer is to leave an older policy exactly where it is because it is still suitable, competitively priced and doing its job properly.
But you only know that by reviewing it.
Sometimes the best outcome is to keep the original cover and top it up.
Sometimes it is to restructure it.
Sometimes it is simply to confirm that it still fits and nothing needs to change.
That reassurance has value too.
At London FS, we do not see reviews as an excuse to meddle. We see them as a sensible check-in.
The detail matters more than people think
Another issue is that life policies are often not set up or maintained with enough care.
Who is the beneficiary?
Is the policy written in trust where appropriate?
Is it still linked to the right purpose?
Does the ownership still make sense?
If it is a joint policy, does it still reflect what both parties want?
These things matter.
A policy can look fine on the surface but still not be structured as cleanly as it should be. That is exactly why regular reviews are worthwhile.
Because when protection is needed, it is usually at one of the worst possible times. That is not when anybody wants to discover something has been overlooked.
Protection should be treated like any other important financial planning
Most people accept the idea of reviewing their mortgage, pension, investments or business arrangements.
Life insurance should be no different.
In our view, protection deserves more attention than it often gets, because it is one of the few areas of planning that is entirely about protecting other people from the financial impact of something going wrong.
That is too important to leave on autopilot.
Our view at London FS
At London FS, we believe life cover should be reviewed properly when there has been a significant change in circumstances, and also periodically even if nothing major seems to have changed.
That includes moving home, remortgaging, having children, changing income, starting a business or simply reaching the point where you have not looked at your policies for years.
The aim is not just to make sure a policy exists.
The aim is to make sure it still does what you think it does.
Because there is a big difference between having cover and having the right cover.
Final thought
Life insurance is one of those things people feel relieved to have arranged. Understandably so.
But arranging it once and forgetting about it is not always enough.
Your life moves on. Your responsibilities change. Your mortgage changes. Your family changes. Your financial position changes.
Your protection should keep up.
Because when it comes to life policies, the real value is not in having one somewhere in the background.
It is in knowing that if it ever needs to step in, it will actually do the job you need it to do.