A client recently came to London FS because they wanted to buy a new family home while keeping their existing property.
They had been advised by another broker the only option they had was to do a let to buy remortgage for the current home and potentially release some equity and use those funds towards the purchase of the new property.
However, during our initial conversation one important point became clear.
The client had no intention of renting their existing property out.
What is a let-to-buy mortgage?
A let-to-buy mortgage is commonly used when someone wants to move home but keep their existing property and rent it out. The existing residential mortgage is replaced with a buy-to-let mortgage and the client takes a new residential mortgage on the property they are buying.
In some cases, equity can also be released from the existing home and used towards the deposit on the new purchase.
For the right client, this can be a very effective solution.
But there needs to be a genuine intention to let the property.
Why does the intention to rent matter?
A buy-to-let lender is assessing the mortgage on the basis that the property will be rented to tenants.
Rental income will often form an important part of the lender’s assessment and the mortgage itself is being offered based on the property being used as an investment.
If a client does not intend to rent the property, a let-to-buy mortgage is not the solution.
If the lender discovers that the mortgage was obtained on a materially different basis from the true intended use of the property, the consequences can be significant.
Depending on the facts, the mortgage conditions and the lender’s investigation, this could potentially result in:
The mortgage application being declined or withdrawn
If discovered before completion, the lender may withdraw the mortgage offer.
The lender investigating the mortgage after completion
The lender may ask for evidence concerning the occupation and use of the property.
A breach of the mortgage conditions
Buy-to-let mortgages contain conditions governing how the property can be occupied and used. Using the property outside those conditions may place the borrower in breach of their mortgage agreement.
The lender requiring the position to be corrected
Depending on the circumstances, this could mean changing the mortgage structure, refinancing or repaying the borrowing.
Enforcement action
In serious circumstances, failure to resolve a breach could ultimately lead to the lender considering enforcement of its security. This would depend on the mortgage contract, the circumstances and the lender’s legal rights.
Potential fraud concerns
Where false information has knowingly been provided to obtain a mortgage, the matter can extend beyond a simple breach of mortgage conditions.
Fraud by false representation is a criminal offence where the statutory requirements are met. The maximum penalty is 10 years’ imprisonment, although the actual consequences in any individual case depend entirely on the facts and any investigation or prosecution.
Source: Fraud Act 2006, section 1 (fraud) and section 2 (fraud by false representation); section 1(3) sets the maximum sentence on indictment at 10 years’ imprisonment.
This is where experienced mortgage advice is important.
At London FS, we do not start with the lender.
We start with the client.
Keeping your existing property does not automatically mean you need to arrange a let-to-buy mortgage.
Depending on your circumstances, a second home mortgage or another residential mortgage structure may be more appropriate.
A second home mortgage can potentially be used where you intend to retain another property for your own use rather than renting it to tenants.
For example, a property might be kept for:
- your own occasional use
- work or commuting
- family use
- longer-term personal plans
- use as a genuine second residence
The important point is that the mortgage structure should reflect what you actually intend to do with the property.
How do second home mortgages work?
There is no single set of criteria for a second home mortgage.
Different lenders take very different approaches.
They may want to understand:
- why you are retaining the existing property
- how often you intend to use it
- who will occupy it
- whether you can afford both mortgages from your income
- your existing mortgage commitments
- your overall level of borrowing
- the equity held within both properties
Some lenders are comfortable with second home arrangements while others may not consider them at all.
That is why lender selection becomes particularly important.
How London FS approached the case
Rather than trying to make the client’s circumstances fit a buy-to-let lender, we stepped back and looked at what the client was actually trying to achieve.
Their objectives were straightforward:
1. Buy a new main residence.
2. Keep their existing property, for their parents to live in.
3. Structure both mortgages correctly from the outset.
Once we understood that, the mortgage strategy changed.
Instead of pursuing a standard let-to-buy structure, we explored second home mortgage options and alternative residential lending solutions that better reflected the client’s intentions.
This may sound like a small distinction.
From a lending perspective, it can be a very important one.
Why experienced mortgage advice matters
With more complex mortgage cases, the lowest rate is not always the first thing we look at.
The first question is: what is the client actually trying to achieve?
Once we understand that, we can work out which lenders and mortgage structures are appropriate.
The right answer will be different for every client.
Our job at London FS is to identify the right structure before an application reaches a lender.
That can help avoid declined applications, unnecessary credit searches and situations where the mortgage arranged does not fit how the property will actually be used.
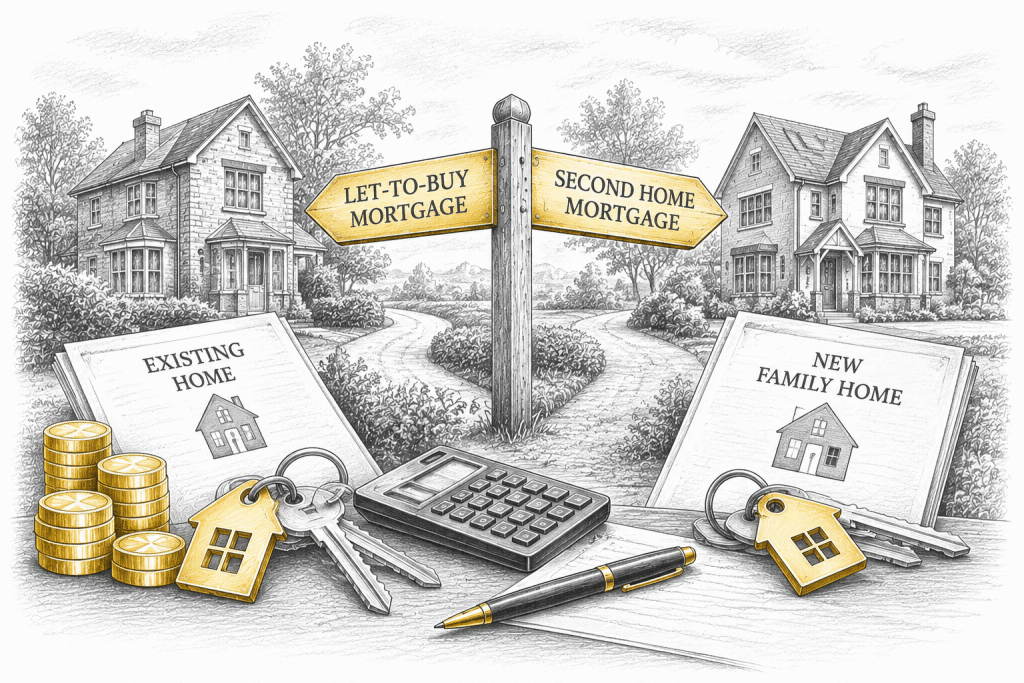
Let-to-buy or second home mortgage?
The difference comes down to what you intend to do with the existing property.
If you genuinely intend to rent it out, a let-to-buy mortgage may be appropriate.
If you want to retain the property for your own use, a second home mortgage or another residential structure may be more suitable.
There may also be situations where neither option is quite right and a more specialist solution is required.
This is particularly relevant for clients with:
- multiple properties
- larger mortgages
- complex income
- company income
- investment portfolios
- high-net-worth circumstances
Buying another home while keeping your existing property?
If you are planning to buy another home while keeping your current property, it is worth getting advice before assuming you need to move the existing mortgage onto buy-to-let.
There may be more than one way to structure the transaction.
At London FS, we work across high-street lenders, building societies, specialist lenders and private banks to help clients find a mortgage structure that fits their circumstances.
We look at the client first, then the mortgage. Not the other way around.
Mortgage availability is subject to individual circumstances and lender criteria. Your property may be repossessed if you do not keep up repayments on your mortgage.Some forms of Buy to Let mortgages for business purposes are not regulated by the Financial Conduct Authority.