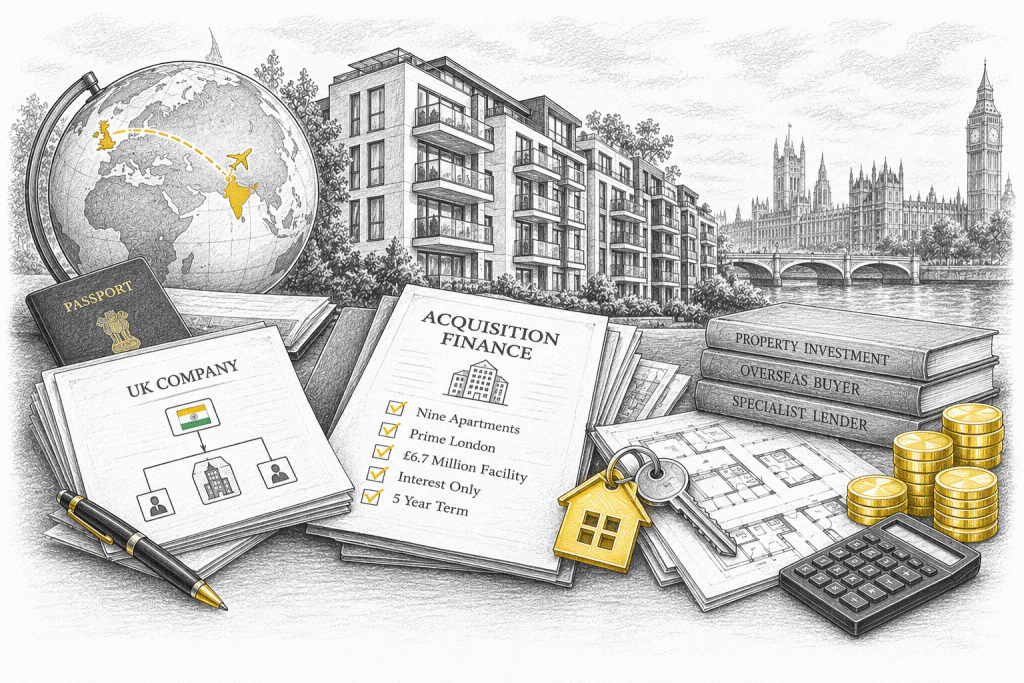
An ultra-high net worth Indian national with no UK visa or residency came to London FS looking to grow their UK property holdings. They already owned one apartment in a prime London development and wanted to buy nine more new build apartments in the same block for £10.8 million, with the purchase made through a newly set-up UK company.
The difficulty was the ownership structure. The borrowing company’s majority shareholder was an Indian trading company, with the remaining shares held by the directors. Plenty of lenders will lend to overseas buyers. Far fewer are comfortable when the shareholder sitting above the borrower is itself an active trading business based overseas. We secured a lender, but they withdrew late in the process. We moved quickly and secured a £6.7 million facility with a specialist lender that was comfortable with both the client profile and the UK property risk. The new terms were better than the original offer, with a one year early repayment charge period.
What Was the Client Looking to Achieve?
The client’s UK footprint was a single apartment in the development. Owning it had given them first-hand knowledge of the building, the location and the rental demand, so when nine more units became available in the same block they saw a chance to turn one flat into a meaningful London portfolio in a single transaction.
Paying cash was an option, but financing was a deliberate choice. By borrowing £6.7 million, the client kept that same amount of their own capital free rather than tying it up in bricks and mortar. For an investor who intends to keep buying, that liquidity counts for as much as the rate.
Why Was This Acquisition Finance Complex?
Lending to a non-resident foreign national already narrows the field. Lenders need to be comfortable with overseas identity and source of wealth checks and with a borrower whose wealth sits largely outside the UK. With only one UK property to their name, the client also had a limited UK track record for a lender to rely on.
The corporate structure narrowed it much further. When a UK company is owned directly by individuals, lenders can look straight through to the people behind it. Here there was an Indian trading company in between. That meant any lender had to underwrite not only the directors and the property, but also an overseas operating business: its accounts, its activities, and how its own commercial risks might affect the borrower. Many credit committees would rather lend to a clean SPV or a passive holding company, so a genuine trading parent in another jurisdiction ruled out a large part of the market before the property was even considered.
Then the original lender withdrew. At that stage the client had committed to the purchase and needed a replacement quickly, from a much smaller pool of lenders than a standard buy to let case would have.
How Did London FS Structure the Finance?
London FS went to a specialist bank with experience of overseas corporate borrowers and prime London residential investment. The lender was prepared to assess the full picture: the ownership chain, the directors, the Indian parent company and the quality of the London stock.
The facility was set at £6.7 million, on an interest only basis over five years with interest paid quarterly. The rate tracks Bank of England base rate. The early repayment charge applies only in the first year, which leaves the client free to refinance or sell individual units from year two without penalty.
The security package was what you would expect for a facility of this kind. It included a legal charge over the apartments, a debenture over the borrowing company and a cash reserve held with the lender. Rental income is routed through an account with the lender, while interest cover and loan to value covenants are tested annually. The lender also set practical conditions after completion, with the flats to be let within six months. Importantly, no corporate guarantee from the Indian parent company was required.
What Was the Outcome?
The purchase completed, taking the client from one apartment in the development to ten. Swapping lenders late in the process did not cost them the deal. It left them with a shorter early repayment charge period and better terms than they had originally accepted. With £6.7 million of their own capital still available, the client is already looking at their next acquisition.
What Are the Risks of This Type of Borrowing?
With an interest only facility, the £6.7 million capital remains outstanding for the full five years. At the end of the term it will need to be repaid, usually through refinancing or selling some or all of the units. Either route depends on property values, lender appetite and market conditions at that point.
Because the rate is variable, any change in Bank of England base rate feeds directly into the quarterly interest cost. It also affects the interest cover covenant. A period of higher rates, longer void periods or falling rents could put pressure on that ratio, while a drop in values could affect the loan to value covenant.
For overseas investors, currency movements add another layer. The rent and the debt are both in sterling, but the investor’s wider wealth may not be. Criteria also vary widely between lenders, and a similar application could be assessed quite differently elsewhere.
What Does This Case Demonstrate?
For overseas investors, the property is often the easy part. Lenders spend most of their time on the structure above it, and a trading company in the ownership chain is exactly the sort of detail that stops many applications before a valuation is ever instructed.
It also shows why having more than one route matters. When a lender withdraws late, the client needs a broker who already knows which lenders will look at the case properly, and who can get a credit approval in place quickly.
“Overseas clients are rarely short of assets. What they need is a lender who understands how those assets are held. Losing a lender late in a deal is stressful, but the right structure in front of the right credit team got us to better terms than we started with.”
Amar Vig, Founder, London FS
Frequently Asked Questions
Yes, some UK and specialist lenders will lend to non-resident foreign nationals, subject to their criteria. Lenders will usually look at the borrower’s nationality, country of residence, source of wealth, deposit and the property being bought.
Some lenders will accept an overseas corporate shareholder, but many will not. Where they do, they will want to understand the full ownership chain down to the ultimate beneficial owners. They may also underwrite the overseas company itself, especially if it is a trading business rather than a holding company.
It is possible, although some lenders limit how much of their lending can sit in one building or development. Larger block purchases are often better suited to specialist lenders or private banks that can assess the investment as a whole.
A bullet repayment means the full loan is repaid in one payment at the end of the term. During the term the borrower pays interest only, in this case quarterly.
An interest cover ratio compares rental income with the interest due on the loan. Lenders set a minimum level as a covenant and test it regularly, so a borrower’s rental performance has to stay above that threshold throughout the facility.
Terms offered before completion are usually not binding on the lender, so a withdrawal is possible. The best protection is a broker with access to several suitable lenders who can move the case quickly if the first option falls away.
Your property may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it.
Some forms of Buy to let mortgages for business purposes are not regulated by the Financial Conduct Authority.