I have become much more opinionated about financial protection, wills and estate planning through my experience in the industry. My view is simple.
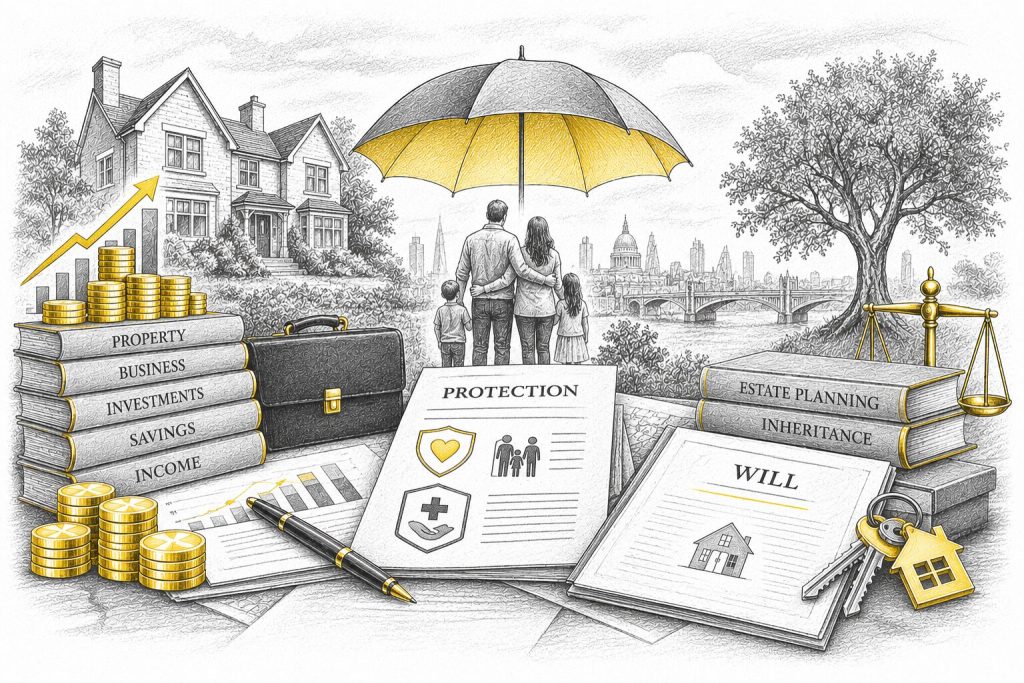
If you have spent years building a home, a business, savings, investments and a lifestyle for your family, but you have done nothing to protect that position or decide what happens to your assets when you die, then the planning is incomplete.
That may sound strong, but I genuinely believe it.
We Focus on Building Wealth, Not Protecting It
We spend a huge amount of time focusing on building wealth.
- Buying property.
- Paying down the mortgage.
- Growing a business.
- Building investments.
- Increasing income.
But far less time asking what happens if the person paying for all of that becomes seriously ill, cannot work or dies.
These Things Actually Happen
The latest ABI protection claims figures show that £8 billion was paid out in protection claims during 2024.
To me, that is not simply an insurance statistic. It is a reminder that these things actually happen.
- Real families.
- Real mortgages.
- Real incomes disappearing.
- Real people dealing with serious illness, injury or bereavement while their financial commitments continue.
Why “Later” Is One of the Most Dangerous Words in Financial Planning
And yet, when discussing protection with clients, I still hear the same things.
“Protection is expensive.”
“I want to see what my finances look like after completion.”
“Let me get the mortgage sorted first.”
“I’ll come back to it later.”
I understand all of those comments. Buying a property is expensive. There are deposits, legal fees, moving costs, furniture and often plenty of other expenses immediately after completion.
But I also think “later” can be one of the most dangerous words in financial planning.
- Later becomes six months.
- Then a year.
- Then five years.
In that time, the mortgage may have increased, children may have arrived, the business may have grown, and the household may have become even more dependent on one or two incomes.
The need for protection has increased, but the conversation has been forgotten.
The Questions That Matter
As an adviser, I can explain the risks. I can show a client what might happen if an income stops, if someone becomes seriously ill or if one person in the household dies. I can explain the options available and what different types of protection are designed to do.
But ultimately, clients also need to understand those risks for themselves. Because protection should never just be about whether someone wants to pay an extra monthly premium. It should be about understanding the potential financial impact of doing nothing.
- What happens to the mortgage?
- What happens to the household income?
- How long would savings last?
- Would the family have to change its lifestyle?
- Would one partner need to work more?
- Would assets have to be sold?
- Would the children be affected financially?
These are the questions that matter.
My job is to make sure the risks are clear. The client’s job is to make an informed decision once they understand what those risks could mean in real life.
That distinction is important.
Only Around 37% of UK Adults Have Made a Will
And the same thing happens with wills.
According to the 2025 National Wills Report, only around 37% of UK adults have made a will. In other words, around 63% have not.
That genuinely surprises me. Because a will is not just something for people with large estates or for later life.
If you have a property, children, savings, business interests or someone financially dependent on you, then in my view you already have a reason to think about what happens if you are no longer here.
Yet the report also found that 34% of adults intend to make a will within the next 12 months. That tells me something important.
Most people probably understand that they should do it. The problem is actually getting around to it.
And that takes me back to the same issue I see with protection.
“I’ll do it later.”
For me, that is not really a plan.
What Happens If You Die Without a Valid Will
If you die without a valid will, you die intestate. That means the law determines how your estate is distributed. Not you.
For unmarried couples, that can be particularly important because a partner does not automatically inherit under the intestacy rules.
Even for married couples with children, the estate may not pass in the simple way people assume.
That is why I struggle when someone says:
“I’m too young to need a will.”
A will is not something you arrange because you expect to die. You arrange it because you have people and assets you care about.
Expensive Compared With What?
The same applies to financial protection. I think we need to challenge the idea that protection is simply “expensive”.
- Expensive compared with what?
- The monthly premium?
- Or the financial cost to a household if one income disappears completely?
Those are very different questions.
Focus on the Biggest Risks First
That does not mean everyone should take every type of protection available. I actually think that would be poor advice.
Good protection planning should be affordable, proportionate and focused on the biggest risks first.
- For one family, that may mean protecting the mortgage with life insurance.
- For another, critical illness cover may be the priority.
- For someone whose household depends heavily on their salary, income protection may be the most important part of the plan.
If the ideal level of cover is not affordable, start somewhere sensible.
- Protect part of the mortgage.
- Protect some of the income.
- Cover the largest risk first.
- Then review it as your circumstances change.
Something appropriate is often better than doing nothing while waiting for the perfect solution.
Wills and Estate Planning: Part of the Same Bigger Picture
And financial protection should not stop with insurance. Wills and estate planning are part of the same bigger picture.
- Who should inherit your assets?
- What happens to the property?
- What happens to the business?
- Who deals with your affairs?
- Who looks after the children?
- Are there inheritance tax considerations?
- Are the right life insurance policies written in trust where appropriate?
These are not always comfortable conversations. But avoiding them does not make them disappear.
Same Event, Very Different Aftermath
Imagine two families. Similar incomes. Similar mortgages. Similar lifestyles.
One has suitable life insurance, critical illness cover or income protection, an up-to-date will and a clear estate plan. The other has none of those things.
While life is going well, there may be no visible difference between them. Then something unexpected happens.
| For one family, there may be insurance money available, some income continuing, clear instructions and some financial breathing space. | For the other, there may be lost income, savings being used, uncertainty over assets and difficult legal and financial decisions at exactly the worst possible time. |
Same event. Very different aftermath.
Three Questions Good Financial Planning Should Answer
That is why I increasingly believe good financial planning should answer three questions:
- How do I build wealth?
- How do I protect what I have built?
- How do I make sure it passes to the right people when I am gone?
Mortgages, protection planning, wills and estate planning should not be looked at in isolation. They are all part of the same bigger picture.
Protecting Wealth Completes the Plan
As advisers, we can identify the risks, explain the consequences and recommend solutions. But good financial planning also requires the client to understand those risks and make a conscious decision about what they are prepared to leave exposed. And if we only focus on building wealth without protecting it or planning what happens afterwards, in my view, we are only doing half the job.