
Why Monthly Payment Matters More Than the Interest Rate?
When people look at mortgage deals, the first thing they usually focus on is the interest rate.
That is understandable. Rates are important and they do affect the overall cost of borrowing. But in reality, we often think too much attention goes on the headline rate and not enough on the question that really matters in day-to-day life:
Can you comfortably afford the monthly payment?
I believe that is where the real focus should be.
A mortgage is not just something that looks good on paper. It is a commitment you live with every month. That is why affordability, cash flow and payment comfort should sit at the heart of the conversation.
The lowest rate does not always mean the best deal
There is a common assumption that the lowest rate automatically means the best mortgage. In practice, it is rarely that simple.
A mortgage should never be judged on rate alone. The right deal depends on the full picture, including the term, the fees, the structure, the client’s plans and how the monthly payment fits into real life.
We regularly see cases where a product with a slightly lower rate is not actually the most suitable option. It may come with higher fees, a shorter term, less flexibility or a monthly payment that feels tighter than it needs to be.
That is why the cheapest-looking deal is not always the best outcome.
What borrowers actually feel is the monthly payment
The interest rate matters, but it is not what you feel each month.
What you feel is the mortgage payment leaving your bank account alongside all the other costs that make up everyday life. Household bills, food, childcare, travel, school fees, insurances, savings and everything else still has to be managed around it.
This is where affordability becomes far more important than the headline rate.
A mortgage should be sustainable. It should allow room for normal life, future plans and the unexpected. It should not leave you constantly stretched just because the deal looked attractive at the outset.
Why this matters even more when remortgaging off an older low rate
This is one of the biggest issues many borrowers are facing now.
A lot of homeowners are coming to the end of fixed rates secured when the market was much cheaper. Moving from one of those older low rates onto a new deal can lead to a noticeable increase in monthly payments, even if the mortgage balance has reduced.
That can be frustrating, but the most useful way to approach it is not simply to ask, “What is the new rate?” It is to ask, “What can we do to keep the payment manageable?”
That is where advice becomes valuable.
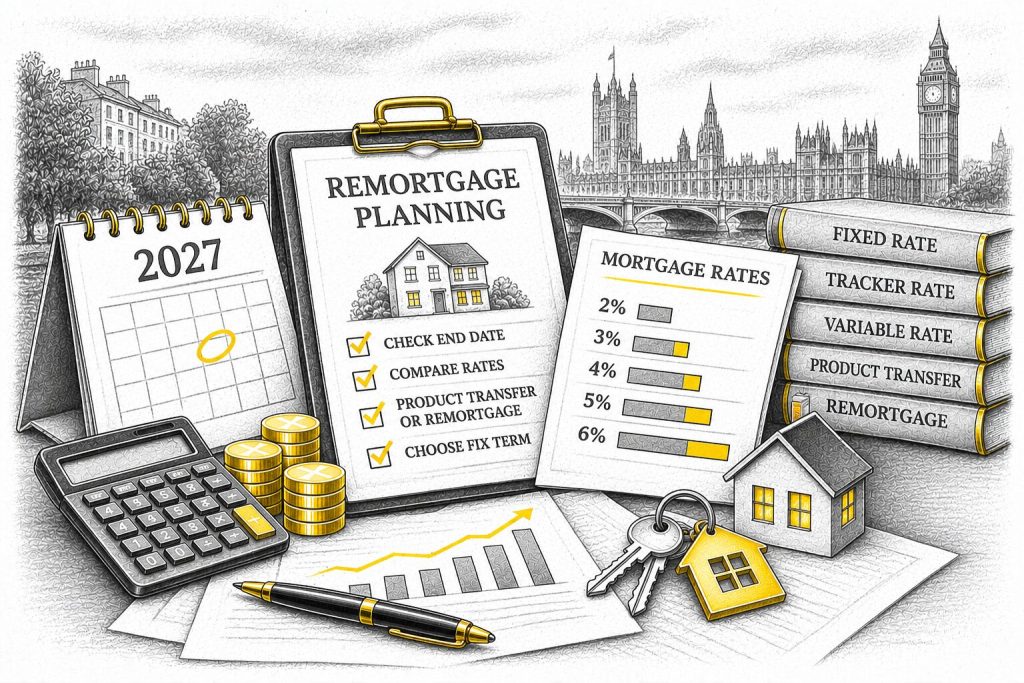
Depending on the circumstances, there may be several ways to manage the transition sensibly. For some, a product transfer with the current lender may be the most straightforward route. For others, a remortgage to a new lender may offer better value overall. In some cases, extending the term can help reduce the monthly commitment. In others, certainty may matter more than chasing the sharpest possible deal.
The right answer depends on the client, not just the rate sheet.
Remortgaging is not just about replacing the old deal
When a fixed rate is ending, many borrowers go straight into rate comparison mode. That is understandable, but it can be too narrow.
A remortgage is an opportunity to review the wider mortgage strategy.
The focus should be on questions such as:
- Is the new payment still comfortable?
- Does the term still suit your circumstances?
- Do you need more breathing space each month?
- Is it worth prioritising certainty for a longer period?
- Would a different lender or structure put you in a stronger position?
For borrowers coming off very low rates, the answer is not always to chase the cheapest new product. Often, it is about finding the right balance between rate, payment, flexibility and peace of mind.
Affordability matters more than maximum borrowing
Just because a lender will allow a certain loan amount does not always mean it is the right figure to take.
There is a big difference between lender affordability and real-life affordability.
At London FS, we are often more interested in what feels comfortable for the client than what the system says is technically possible. A mortgage should work around your life, not dominate it.
That means allowing room for changes in income, rising household costs, future family plans or unexpected expenses. Borrowing to the limit may work on paper, but that does not always make it sensible.
Structure matters just as much as price
This is where proper mortgage advice makes a difference.
Two deals can look similar at first glance, but once you take into account the monthly payment, the fees, the term and the overall flexibility, one option often stands out more clearly than the other.
Sometimes the better option is the one that reduces payment pressure now and gives the client more control. That may mean a slightly longer term. It may mean lower upfront costs. It may mean fixing for longer to create certainty. It may simply mean choosing the option that feels more sustainable.
That is not settling. That is making a practical financial decision.
The best mortgage should support real life
A mortgage should fit into the client’s wider life, not exist in isolation.
That is why the monthly payment matters so much. It is the part that determines whether the mortgage feels manageable in the real world.
If one income changes, if childcare costs increase, if business income fluctuates, or if other household expenses rise, the mortgage still needs to be workable. That is why we always believe affordability deserves more attention than the headline rate alone.
Our view at London FS
At London FS, we care about rates, but we do not believe rate alone should drive the advice.
We look at the overall structure, the monthly payment, the client’s circumstances and how the mortgage fits their wider plans. That is especially important for homeowners coming off older low fixed rates, where the priority is often making sure the new payment remains realistic and sustainable.
The best mortgage is not always the one with the lowest number next to it.
It is the one that works properly for the client.
Speak to London FS
If your current mortgage deal is ending, or you are trying to understand how rate changes may affect your monthly payment, we can help you review the options properly.
At London FS, we look beyond the headline rate and focus on what is affordable, practical and right for your circumstances.
Get in touch to discuss your remortgage or mortgage options with our team.